Ohio Is Letting Red Diesel Run on Highways — Here’s Exactly What’s Legal
The short answer: until 31 December 2026, you can legally run dyed (red) diesel in a highway vehicle in Ohio without facing the usual $1,000-or-more penalties — but the tax itself is only deferred, not forgiven, and everything snaps back on 1 January 2027. On 21 October 2026, Governor Mike DeWine signed Executive Order 2026-05D, “Use of Dyed Diesel on Public Highways,” directing the Ohio Tax Commissioner to waive state penalties for dyed-diesel highway use through the end of the year and to suspend discretionary enforcement. The Ohio Department of Taxation followed with its own announcement that it will not impose state penalties for the sale, distribution, or use of dyed diesel on highways or waterways during the relief period.
This is the state layer of a two-layer relief package. The federal layer arrived first: a presidential executive order on 5 October, followed by IRS relief (IR-2026-122 on 14 October and IR-2026-125 on 21 October) suspending federal penalties and even the Form 720 reporting for the deferred tax. But the single most important sentence in this whole story comes from a farm CPA who watched the rumours spread: a lot of farmers are hearing “tax-free” when the order says “pay later.” Read this guide before you fill up — the waiver is real, generous, and temporary, and the traps are all in what it does not cover.
Key Facts at a Glance
| Item | Detail |
|---|---|
| What changed | Ohio Executive Order 2026-05D (signed 21 Oct 2026) + Ohio Department of Taxation penalty waiver |
| Relief period | Through 31 December 2026 (federal relief retroactive to 1 Oct 2026) |
| Who is covered | Anyone — farmers, truckers, any motorist; sellers and distributors too |
| State penalties waived | Yes — R.C. 5735.124 penalties ($1,000 or $10/gal, repeat-offence multiplier) suspended |
| Federal penalties waived | Yes — I.R.C. §6715 penalties suspended nationwide (IRS IR-2026-122) |
| Federal excise tax (24.4¢/gal) | Deferred, NOT forgiven — guidance on paying it later still pending |
| Ohio fuel tax on the diesel | No deferral needed — the H.B. 519 holiday already cuts it to ~zero through 2 Jan 2027 |
| Form 720 reporting | Temporary IRS relief — no filing needed solely to report this liability (IR-2026-125) |
| After 31 December | All normal penalties return; residual red dye stays detectable — plan your tanks now |
What Dyed Diesel Actually Is (and Isn’t)
Dyed diesel — “red diesel,” “off-road diesel” — starts life as ordinary ultra-low-sulphur diesel. The red colour comes from a chemical marker (a Solvent Red dye) added at the terminal to flag fuel that was sold without the federal and state on-road excise taxes. It is chemically the same 15-parts-per-million ULSD as the clear diesel at the truck stop pump. That answers the most common mechanical worry head-on: no, red diesel will not damage your engine. The dye is purely a tax-enforcement marker.
Because the tax was never paid on it, dyed diesel has always been legal only for off-road use: tractors, combines, construction equipment, generators, and farm machinery that never touches a public road. Putting it in a highway vehicle has always been treated as tax evasion — enforced with dip tests at weigh stations and some of the steepest per-violation penalties in the tax code. That is the baseline the October 2026 orders temporarily overturn.
What Happened: The Two Layers of Relief
The federal layer
On 5 October 2026, the President signed Executive Order 14435, “Emergency Tax Relief on Diesel Fuel.” It directed the Treasury Secretary to defer diesel fuel tax payment obligations under 26 U.S.C. §4041 incurred between 5 October and 31 December 2026, without penalties or interest, and to direct the IRS not to impose the dyed-fuel penalties of 26 U.S.C. §6715 for highway use of dyed diesel during that period.
The IRS followed through in two releases:
- IR-2026-122 (14 October 2026): nationwide, the IRS will not impose a penalty when dyed diesel is sold for use or used on highways. The relief is retroactive to 1 October 2026 and runs through 31 December 2026, and it is available to any person — sellers and users alike. During the period, ordinary collection and enforcement are suspended: IRS Fuel Compliance Officers have been reassigned, there are no federal on-road dyed-fuel inspections, taxpayers need not maintain records to substantiate eligibility, sellers and distributors are under no obligation to investigate or document end use, and covered penalties include failure to make semimonthly deposits and failure to maintain adequate records.
- IR-2026-125 (21 October 2026): temporary administrative relief from reporting and recordkeeping under I.R.C. §4041(a). The IRS will not challenge failures to meet return-filing, reporting, or recordkeeping requirements that are solely attributable to §4041(a) liability from taxable uses of dyed diesel on or after 1 October 2026 and before 1 January 2027. In plain terms: you do not have to file Form 720 (Quarterly Federal Excise Tax Return) solely to report this liability, you do not have to report it on an otherwise-required Form 720, and you do not have to create or keep records solely to substantiate it. No civil penalties or additions to tax apply solely for those covered failures — and this holds even if the filing deadline falls after 31 December 2026, with no later reconstruction of records required. (If you must file Form 720 for other liabilities, you still file.) The IRS also said it is considering a grace period for the residual-dye problem — but as of late October, nothing has been issued.
The Ohio layer
On 21 October 2026, Governor DeWine signed Executive Order 2026-05D, “Use of Dyed Diesel on Public Highways.” The order directs the Ohio Tax Commissioner to waive penalties for the use of dyed diesel fuel on Ohio’s public highways through 31 December 2026 and to suspend discretionary enforcement and investigation of the state’s dyed-diesel restrictions (under R.C. Chapter 5735) during the same period. An attorney summary from Ohio State University’s Farm Office confirms the order applies to anyone — not just farmers.
The Ohio Department of Taxation then announced — as reported by Bloomberg Law on 23 October, citing the Department’s guidance — that it will not impose state penalties for the sale, distribution, or use of dyed diesel fuel on public highways or waterways during the federal penalty-relief period ending 31 December 2026. The legal hook is R.C. 5735.124 itself, which authorises the Tax Commissioner to reduce or waive assessed penalties; the Commissioner is exercising that authority for the relief period.
One Ohio-specific wrinkle worth knowing: unlike the federal side, Ohio does not need to defer its own fuel-tax liability on dyed diesel bought during this period — because Ohio’s 90-day motor fuel tax holiday (H.B. 519) is already running. The holiday cut the state diesel tax from 47¢ per gallon to a nominal 0.0001¢ from 4 October 2026 through 2 January 2027. Full dates, savings maths, and FAQs are in our Ohio gas tax holiday (H.B. 519) guide.
Why now: the timeline
- 6 October 2026: Ohio farm groups (Ohio Farm Bureau, Ohio Corn & Wheat Growers, Ohio Soybean Association) write to Governor DeWine asking for temporary suspension of dyed-diesel restrictions.
- 5 October 2026: Presidential Executive Order 14435 signed (“Emergency Tax Relief on Diesel Fuel”).
- 14 October 2026: IRS IR-2026-122 — nationwide penalty suspension, retroactive to 1 October.
- 19 October 2026: USDA announces the separate $8 billion Harvest Fuel Relief Program (diesel-loss payments through the Commodity Credit Corporation — a different programme; don’t confuse it with the tax waiver).
- 21 October 2026: DeWine signs EO 2026-05D; IRS issues IR-2026-125 (Form 720 reporting relief).
- 23 October 2026: Ohio Department of Taxation penalty waiver announced.
- 31 December 2026: all relief ends. 1 January 2027: normal rules return.
The backdrop is a genuine fuel crunch: Ohio diesel averaged $6.24 per gallon in late October (AAA), national averages set records around $6.28–$6.52 in September, driven by supply disruption from the Iran conflict and the ExxonMobil Joliet refinery unit shutdown. With harvest at its most fuel-intensive point, Ohio Farm Bureau president Bill Patterson said the order gives “much-needed flexibility for farmers and partners across the agricultural supply chain,” while Ohio Corn & Wheat Growers president Eric Tipton noted it helps farmers “finish harvest and provide some financial breathing room heading into 2027.”
Who Qualifies: Not Just Farmers
The most persistent misunderstanding about this waiver is that it is a farm programme. It is not. Both the federal relief and the Ohio order apply to any person:
- Farmers — the headline beneficiaries: pulling from on-farm tanks of cheaper off-road diesel to fuel trucks hauling grain to elevators or markets on public roads, which has generally been prohibited until now.
- Truckers and fleet operators — any motorist running a diesel highway vehicle, subject to the practical cautions below.
- Sellers and distributors — covered for selling or distributing dyed diesel for highway use, and under IR-2026-122 they are under no federal obligation to investigate or document what the buyer does with it.
- Waterways — Ohio’s waiver expressly covers highway and waterway use.
That said, “anyone is covered” is not the same as “everyone should do it.” The practical playbooks below explain the judgement calls for farmers and truckers separately.
Waived vs. Still Owed: The Core of the Whole Story
This is the section to read twice, because it is where the expensive mistakes live.
What is WAIVED through 31 December 2026
- Federal §6715 penalties — the greater of $1,000 or $10 per gallon of dyed fuel involved, per violation, with escalation for repeat offences — suspended nationwide (IR-2026-122).
- Ohio R.C. 5735.124 penalties — the Tax Commissioner is exercising the statute’s reduce-or-waive authority: no state penalties for sale, distribution, or use on highways or waterways during the relief period.
- Federal enforcement — no on-road dyed-fuel inspections; Fuel Compliance Officers reassigned; no records needed to prove eligibility; sellers need not investigate end use.
- Ohio discretionary enforcement and investigation — suspended under EO 2026-05D.
- Form 720 reporting and recordkeeping for this liability — temporary relief under IR-2026-125, as detailed above.
- Semimonthly deposit penalties related to the deferred liability — covered by IR-2026-122.
What you STILL OWE
- The federal excise tax itself — 24.4¢ per gallon under §4041(a). The presidential order defers payment obligations incurred 5 October–31 December 2026; it does not cancel them. As of late October, the Treasury/IRS guidance explaining how and when that deferred tax gets paid (the expected §7508A guidance) had not yet been issued. The FarmCPA Report’s warning is the one to tape to your dashboard: “a lot of farmers are hearing ‘tax-free’ when the order says ‘pay later.'” Do not assume the 24.4¢ is gone.
- Ohio fuel tax after the holiday. During the H.B. 519 holiday the state rate is effectively zero anyway, so there is nothing to defer. But the holiday ends 2 January 2027 — two days after the dyed-diesel waiver ends.
- Everything in other states. Federal relief does not waive any state’s fuel taxes or penalties. Ohio has acted; many states have issued their own relief, but not all — and the terms differ. North Carolina’s October notice, for example, is farming-only and still requires the state excise tax to be paid.
Bottom line: penalties = paused; the federal tax = postponed. Keep records of what you buy and burn anyway — the IRS says you don’t have to, but when the deferred-tax guidance lands, the people with receipts will sleep better.
Normal Penalties — What Returns on 1 January
To appreciate what the waiver is saving you, here is what the law normally does to dyed diesel found in a highway vehicle:
- Federal (26 U.S.C. §6715): the greater of $1,000 or $10 per gallon of dyed fuel involved, per violation. Repeat offences escalate: the $1,000 floor rises by $1,000 for each prior penalty (second offence: $2,000 floor; third: $3,000, and so on). Corporate officers and employees can face joint and several liability.
- Ohio (R.C. 5735.124): for a seller or distributor who knew (or had reason to know) of highway or waterway use — $1,000 or $10 per gallon, whichever is greater, and/or licence revocation. For the consumer or vehicle operator — $1,000 or $10 per gallon of the vehicle’s fuel-supply-tank capacity, whichever is greater (note: tank capacity, not the gallons you actually burned). Repeat offences: the penalty is multiplied by the number of prior penalties. The same statute gives the Tax Commissioner power to reduce or remit a penalty — the authority behind the current waiver.
- Enforcement: under normal rules, dyed fuel is policed with dip tests at weigh stations and roadside inspections, and egregious cases can bring vehicle seizure. All of that is stood down only until 31 December.
Practical Playbook for Farmers
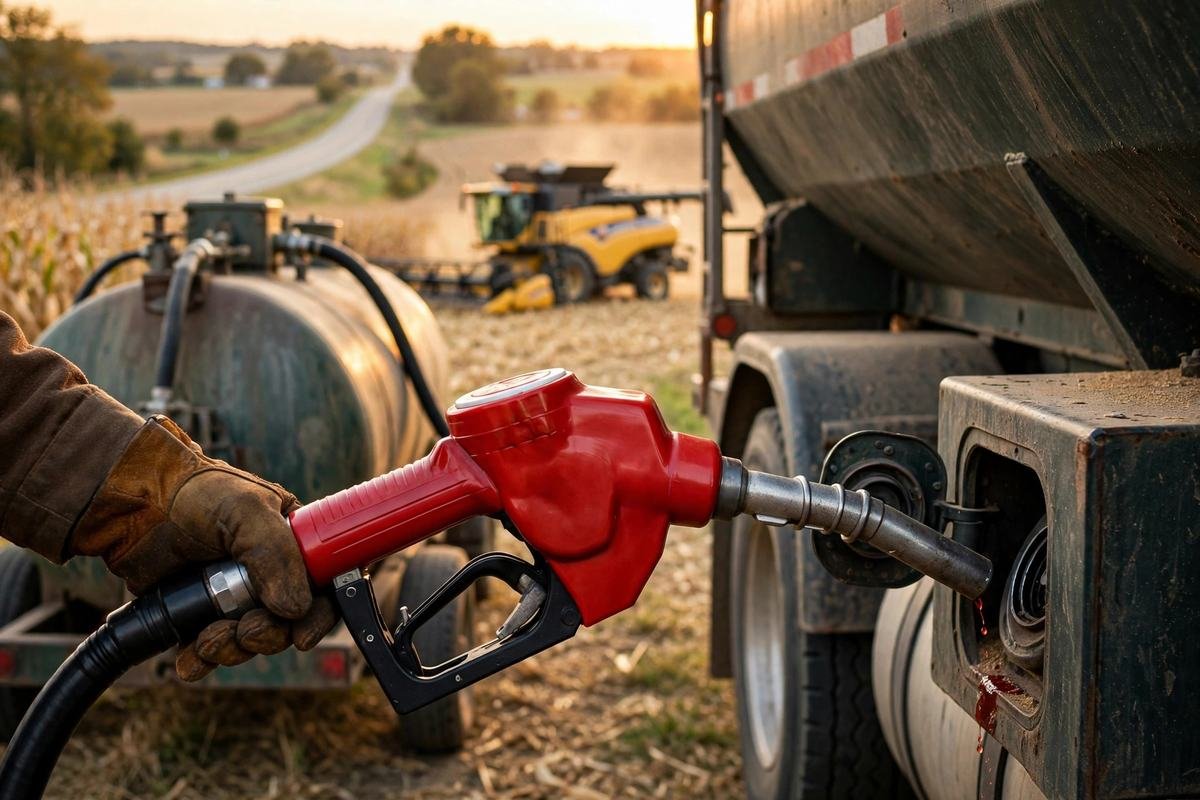
You are the group this was designed around — harvest is the most fuel-intensive stretch of the year, and diesel above $6 a gallon is shredding already thin margins. The Ohio order specifically lets you do what was previously prohibited: pull from your on-farm tanks of off-road diesel to fuel trucks hauling grain to elevators and markets on public roads.
- It’s legal through 31 December — state penalties waived, enforcement suspended, federal penalties suspended. You do not need a permit or an application.
- Keep receipts anyway. The IRS says no records are needed to substantiate eligibility, but the 24.4¢/gal federal tax is deferred, not forgiven. When the pay-later guidance arrives, dated purchase records are your proof of what falls inside the deferral window.
- Don’t confuse this with the USDA money. The separate $8 billion Harvest Fuel Relief Program (announced 19 October) pays for diesel losses through the Commodity Credit Corporation — a different programme with its own rules.
- Plan your tanks for January. Red dye lingers at parts-per-million levels long after you switch back to clear diesel. Run dyed stocks down before year-end and consider flushing tanks — North Carolina’s tax authority is already advising exactly that. See the 1 January section below.
- Bennett Musselman of the Ohio Soybean Association and the other farm groups that lobbied for this in early October expect it to matter most for exactly your situation: moving this year’s crop while diesel is at record prices.
Practical Playbook for Truckers
You are covered — the relief is not farmers-only — but your situation has more moving parts. Work through these before you fill with red:
- Check every state on your route. Federal relief suspends federal penalties everywhere, but it does not waive any state’s penalties or taxes. Ohio has waived; many states have issued similar relief; some have not, and terms vary (North Carolina’s is farming-only, for instance). Do not carry red dye into a state that hasn’t waived its own rules. IFTA reporting gets complicated when the fuel in your tanks was bought under one state’s relief and burned in another — the Owner-Operator Independent Drivers Association is flagging exactly this.
- Call the seller first. Under IR-2026-122, sellers are under no federal obligation to document end use — but in practice, truck-stop operators are nervous. The national truck-stop association’s lobbyist has said the federal guidance stayed murky enough that many members see too much risk. Some sellers may simply refuse to sell dyed diesel for highway use. Confirm before you route around it.
- The tax is deferred, not gone, for you too. The 24.4¢/gal §4041 liability sits in limbo until Treasury issues the pay-later guidance. Budget for it.
- Weigh-station dip tests are stood down federally — Fuel Compliance Officers are reassigned and there are no federal on-road inspections during the relief period — but that is a suspension, not a repeal. It ends 31 December.
- Context that may help your schedule: the Federal Motor Carrier Safety Administration has also issued a hours-of-service waiver for fuel haulers (through 15 December) to keep diesel moving — one more sign of how tight supply is right now.
What Happens on 1 January 2027 — Plan Now
Every layer of relief ends on 31 December 2026. On 1 January 2027, the normal penalty regimes — federal §6715 and Ohio R.C. 5735.124, in all their $1,000-or-$10-a-gallon glory — are back in force, along with inspections and dip tests.
The trap is residual dye. The red marker doesn’t wash out when you switch back to clear diesel; forum mechanics and fuel-tax professionals alike note it remains detectable at just a few parts per million — practically “forever” in a tank that’s never cleaned. A tank dipped in February could still test positive for red you legally burned in November. Practical steps:
- Run dyed stocks down before year-end so you’re not carrying red into January.
- Consider flushing tanks before the new year — this is already the official advice from North Carolina’s revenue department for its own waiver.
- Do not assume an IRS grace period. IR-2026-125 says the IRS is merely considering “an appropriate grace period or other mitigation” for residual dye — nothing has been issued. Plan as if 1 January is a hard line.
- Mixing red and clear diesel now means red later. Every gallon of red you blend into a tank extends the detection window.
- Watch for the deferred-tax guidance. Treasury still owes the rules on when and how the deferred 24.4¢/gal gets paid. If you’re juggling other deadline pressure as the year turns, our Ohio tax extension guide covers buying time on the state income-tax side.
What the Waiver Does NOT Cover
- Gasoline vehicles. This is diesel-only relief. Red diesel in a petrol car was never a thing and still isn’t.
- A fix for $6 diesel. The waiver removes penalties; it doesn’t lower the price of fuel. Ohio’s separate gas tax holiday is the piece actually cutting pump prices (47¢/gal off diesel through 2 January).
- Automatic state coverage elsewhere. Again: federal ≠ state. Each state decides for itself.
- Forgiveness of the federal tax. Worth saying a third time, because it’s the misconception that will cost people money: deferred is not forgiven.
The waiver is one piece of an unusual autumn for Ohio tax news — alongside the federal disaster-relief deadline extensions for seven Ohio counties and the property tax levies on the 3 November ballot. We’ll update this guide if Treasury issues the deferred-tax payment rules or the IRS announces a residual-dye grace period.
Frequently Asked Questions
Q: Can I put red diesel in my pickup or truck right now in Ohio?
A: Yes — through 31 December 2026. Governor DeWine’s Executive Order 2026-05D and the Ohio Department of Taxation’s waiver suspend state penalties for dyed-diesel highway use, and the IRS has suspended federal penalties nationwide for the same period. The relief covers anyone, not just farmers. After 31 December, the normal penalties return.
Q: Is red diesel the same fuel as regular diesel — will it hurt my engine?
A: It is chemically the same ultra-low-sulphur diesel sold at the pump; the red dye is purely a tax marker added to flag untaxed fuel. It will not damage your engine. The prohibition was always about unpaid tax, never about fuel quality.
Q: Can I mix red diesel and clear diesel in the same tank?
A: Physically yes, but think about January. The red marker remains detectable at just a few parts per million, so any red you blend in now extends the window in which a dipped tank could test positive after the waiver ends. Run dyed stocks down before year-end rather than mixing.
Q: Do I still owe any tax, or is the fuel now tax-free?
A: You still owe the federal excise tax — 24.4¢ per gallon under I.R.C. §4041(a). The October orders defer it; they do not forgive it, and the Treasury guidance on when and how to pay it later had not been issued as of late October. In Ohio, no state fuel-tax deferral is needed because the H.B. 519 holiday already cuts the state diesel tax to effectively zero through 2 January 2027.
Q: Do I need to file IRS Form 720 because of the waiver?
A: No — not solely for this. Under IRS notice IR-2026-125, you do not have to file Form 720 (Quarterly Federal Excise Tax Return) just to report the deferred §4041(a) liability, report it on an otherwise-required Form 720, or keep records solely to substantiate it, and no penalties apply for those covered gaps. If you must file Form 720 for other liabilities, you still file.
Q: Can police or inspectors still test my tank or ticket me?
A: In Ohio, discretionary enforcement and investigation of the dyed-diesel rules are suspended through 31 December under the governor’s order. Federally, IRS Fuel Compliance Officers have been reassigned and there are no federal on-road inspections during the relief period. But other states set their own rules — a state trooper in a state that hasn’t waived its own dyed-fuel law can still fine you.
Q: I drive through other states — am I covered outside Ohio?
A: Only partly. The federal penalty suspension is nationwide, but federal relief does not waive any state’s fuel taxes or penalties — each state decides separately. Ohio has waived; many states have issued their own relief; some have not, and terms differ (North Carolina’s is farming-only, for example). Check every state on your route and don’t carry red dye into one that hasn’t waived.
Q: What should I do before 31 December to avoid penalties in January?
A: Three things: (1) run your dyed-diesel stocks down so you’re not carrying red into January; (2) consider flushing fuel tanks — residual dye is detectable at parts-per-million levels, and no IRS grace period has been issued yet; (3) keep purchase records even though the IRS says you don’t have to — you’ll want them when the deferred-tax payment guidance arrives.
Sources
- IRS Newsroom — IR-2026-122, dyed diesel fuel penalty relief (14 Oct 2026): https://www.irs.gov/newsroom/irs-provides-dyed-diesel-fuel-relief-related-to-excise-tax-following-president-trumps-executive-order
- IRS via GovDelivery — IR-2026-125, §4041(a) reporting and recordkeeping relief (21 Oct 2026): https://content.govdelivery.com/accounts/USIRS/bulletins/4300162
- Bloomberg Law — “Ohio Tax Department Announces Waiver of Dyed Diesel Penalties Through Year-End” (23 Oct 2026): https://news.bloomberglaw.com/daily-tax-report-international/ohio-tax-department-announces-waiver-of-dyed-diesel-penalties-through-year-end
- Bloomberg Law — “Ohio Governor Issues Executive Order Waiving Certain Dyed Diesel Fuel Penalties, Enforcement” (22 Oct 2026): https://news.bloomberglaw.com/daily-tax-report-international/ohio-governor-issues-executive-order-waiving-certain-dyed-diesel-fuel-penalties-enforcement
- OSU Farm Office — Peggy Kirk Hall (attorney), “DeWine and Trump act on high diesel fuel prices” (22 Oct 2026): https://farmoffice.osu.edu/blog/thu-10222026-319pm/dewine-and-trump-act-high-diesel-fuel-prices
- Ohio Society of CPAs — “IRS, Ohio provide temporary dyed diesel fuel relief” (23 Oct 2026): https://ohiocpa.com/for-the-public/news/2026/10/23/irs–ohio-provide-temporary-dyed-diesel-fuel-relief
- Ohio Farm Bureau — “Ohio Farm Bureau applauds Gov. DeWine dyed diesel executive order” (22 Oct 2026): https://ofbf.org/2026/10/22/ohio-farm-bureau-applauds-dewine-dyed-diesel-executive-order/
- Ohio’s Country Journal — “Farmers in Ohio get temporary use of dyed diesel fuel” (22 Oct 2026): https://ocj.com/2026/10/farmers-in-ohio-get-temporary-use-of-dyed-diesel-fuel/
- Farm and Dairy — “Ohio suspends dyed-diesel enforcement on highways through end of year” (Oct 2026): https://www.farmanddairy.com/news/ohio-suspends-dyed-diesel-enforcement-on-highways-through-end-of-year/934363.html
- Morning Ag Clips — “Ohio Farm Groups Applaud Gov. Dewine Dyed Diesel Executive Order” (Oct 2026): https://www.morningagclips.com/ohio-farm-groups-applaud-gov-dewine-dyed-diesel-executive-order/
- Canton Repository (USA Today) — “Can I buy red diesel in Ohio? What to know about the fuel’s new rules” (22 Oct 2026): https://www.cantonrep.com/story/business/economy/2026/10/22/can-i-buy-red-diesel-in-ohio-what-to-know-about-the-fuels-new-rules/92377208007/
- Thomson Reuters Tax & Accounting — “IRS suspends dyed diesel penalties following executive order”: https://tax.thomsonreuters.com/news/irs-suspends-dyed-diesel-penalties-following-executive-order/
- TenFour Compliance — “Fuel Tax Holiday and Dyed Diesel on IFTA Returns”: https://www.tenfourcompliance.com/help/fuel-tax-holiday-dyed-diesel-ifta-return
- FarmCPA Report — “Dyed Diesel on the Highway” (13 Oct 2026): https://www.farmcpareport.com/p/dyed-diesel-on-the-highway-what-the
- KPMG TaxNewsFlash — IR-2026-125 reporting relief summary (Oct 2026): https://kpmg.com/us/en/taxnewsflash/news/2026/10/irs-reporting-recordkeeping-dyed-diesel-excise-tax-relief.html
- Land Line (OOIDA) — “Diesel prices stay at record levels; diesel relief rolls on” (22 Oct 2026): https://landline.media/diesel-prices-stay-at-record-levels-diesel-relief-rolls-on/
- Ohio Revised Code, Chapter 5735 (motor fuel tax; §5735.124 penalties): https://codes.ohio.gov/ohio-revised-code/chapter-5735
- LegalClarity — dyed diesel penalty mechanics under 26 U.S.C. §6715: https://legalclarity.org/what-is-the-fine-for-running-off-road-diesel/